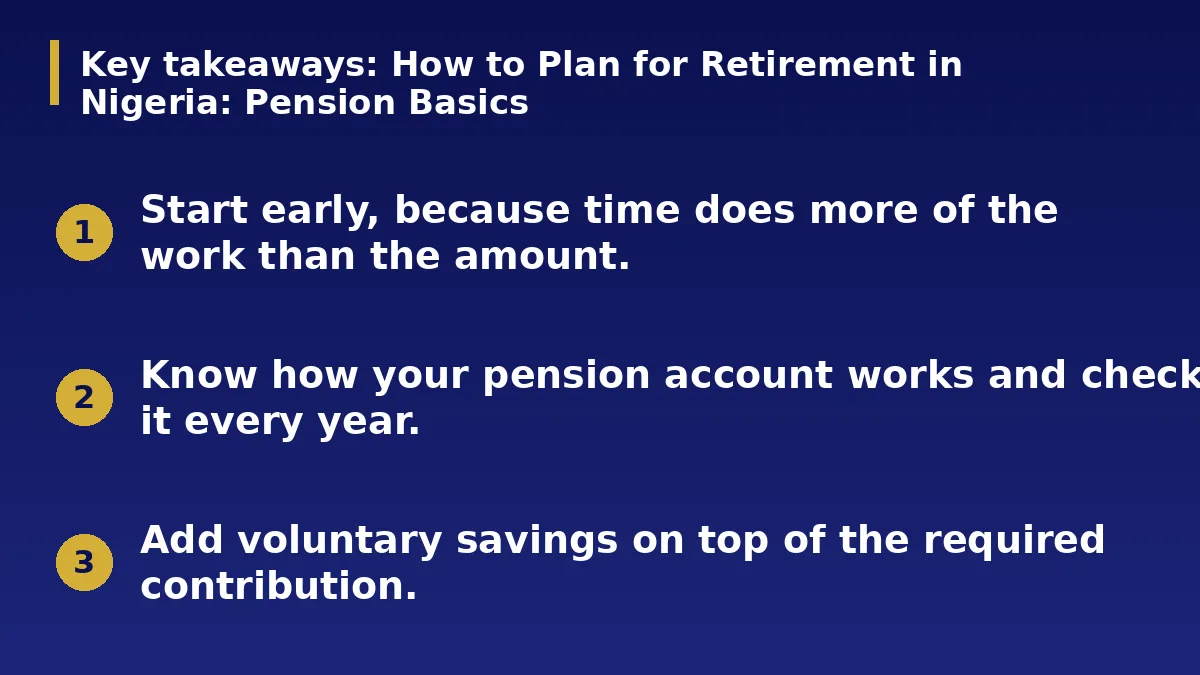
- Start early, because time does more of the work than the amount.
- Know how your pension account works and check it every year.
- Add voluntary savings on top of the required contribution.
The Short Answer
Retirement can feel distant, but the earlier you plan, the smaller the monthly effort. In Nigeria, most employees contribute to a retirement savings account under the contributory pension system. Understanding it, and adding your own savings, is the best protection against depending on others later.
How the Contributory Scheme Works
Under the scheme, you and your employer pay a percentage of your earnings into a retirement savings account managed by a licensed pension fund administrator. The money is invested and builds up until retirement. Check the current rates and rules with the regulator, because they can change.
Self-employed people can also open an account and contribute voluntarily.
Check Your Account Every Year
Log in or request your statement at least once a year. Confirm that your employer is paying in on time and that your personal details are correct. Missing contributions are easier to fix early than ten years later.
Compare the fund options available to you. Younger savers may accept more growth risk, while those near retirement usually prefer safer funds.
Add Voluntary Savings
The required contribution may not be enough for the lifestyle you want. Set a target, such as saving an extra amount each month into your pension account or a regulated long-term investment. Use automatic transfers so you do not rely on willpower.
Increase the amount every time your income rises, even slightly.
Plan Beyond Money
Retirement planning includes health, housing and family support. Think about where you will live, how you will cover medical costs and whether you will earn something from a part-time activity.
Build skills and a small income stream you can continue as you age, and write down your plan so your family knows your wishes.
A Simple Example
Suppose you are 30 and plan to retire at 60. If you save an extra 20,000 naira a month for thirty years, that is 7,200,000 naira before any growth. Starting at 40 and saving the same amount gives only 4,800,000. The difference comes from starting ten years earlier.
Real results depend on investment returns, fees and inflation, so treat any example as an illustration and not a promise.
Mistakes to Avoid
Do not ignore your pension statement for years. Do not withdraw from savings early unless the rules clearly allow it and you understand the cost. Avoid putting everything into one risky investment because someone promised fast growth.
Another mistake is assuming family will cover you. Many people cannot, even with the best intentions, so a personal plan matters.
Questions to Ask Your Administrator
Ask which fund suits your age, what fees are charged, how often you get statements and what the process is for retirement or early exit. Ask how to add voluntary contributions.
Keep written answers and update your records if you change jobs, so your account follows you.
Action Checklist
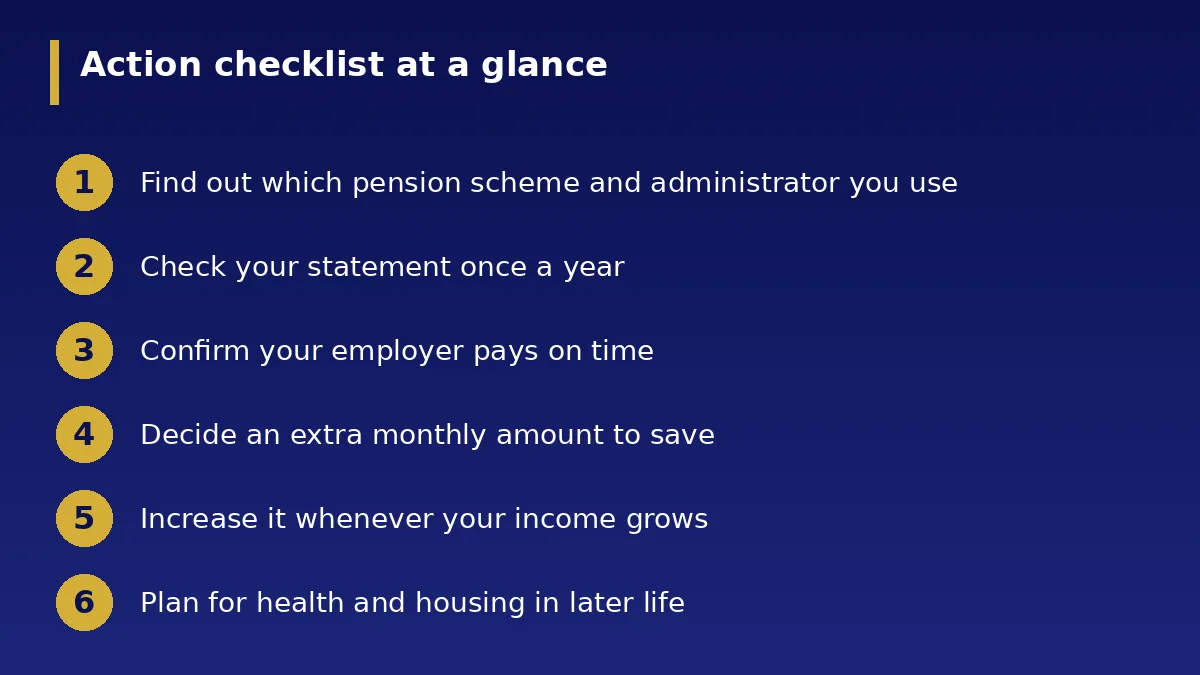
- Find out which pension scheme and administrator you use
- Check your statement once a year
- Confirm your employer pays on time
- Decide an extra monthly amount to save
- Increase it whenever your income grows
- Plan for health and housing in later life